Buying a home in Japan? Here’s how the mortgage process works, and what foreign residents should check before applying.
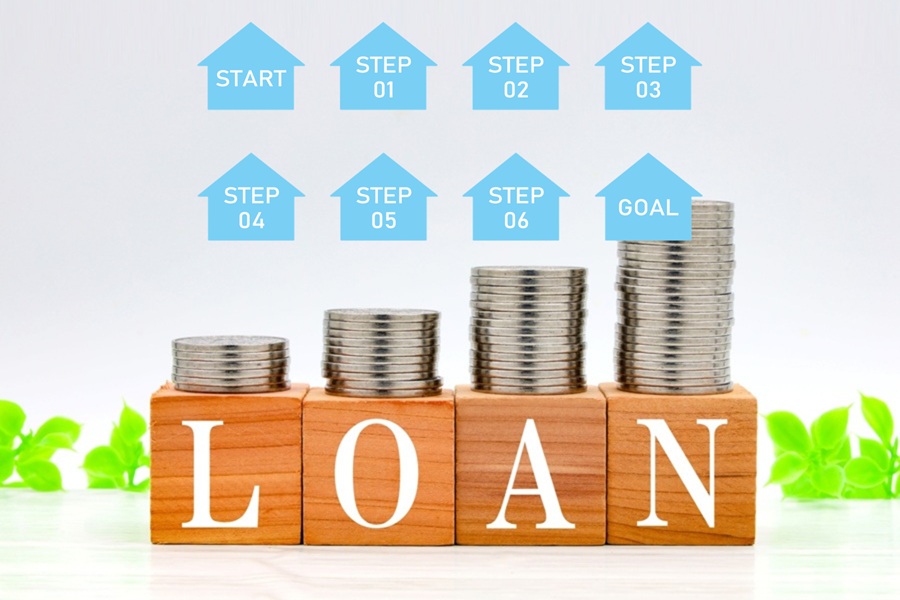
(写真はイメージです)
The Home Loan Process, Step by Step
When you apply for pre-screening on a home loan, you’ll need to provide details about the property you intend to purchase. It’s standard practice for prospective buyers to go through pre-screening only after they’ve decided on a specific property.
Pre-screening usually takes about 20 minutes if you have everything ready. If you’re employed, you’ll typically need:
- Your annual income, as shown on last year’s salary withholding certificate
- Your company’s capital and number of employees
- The year and month you started at your company, plus its address and phone number
- How long you’ve lived in Japan and your current visa status
- Your current address and mobile number
- Full details of the property you wish to purchase
Keep your ID and the property’s sales brochure on hand, as both usually need to be uploaded.
The Six Main Steps, at a Glance
- Property Viewing
- Submit Letter of Intent (LOI)
- Pre-Screening Approved
- Contract Signed & Earnest Money Paid
- Final Screening Approved
- Balance Payment & Loan Disbursement
Because pre-screening is based only on the information you provide, approval at this stage doesn’t guarantee approval later. Before accepting your LOI, sellers want confidence that you’re highly likely to pass final screening too. That’s because most purchase contracts include a clause allowing you to cancel without penalty if your mortgage isn’t approved by the bank — understandably, sellers want to avoid that outcome. If you’re not confident the bank will approve your application, a seller may hesitate to accept your LOI in the first place.
What Foreign Buyers Need to Know About Securing a Home Loan in Japan
Navigating Japanese mortgage requirements as an international resident can be complex. While anyone/ can legally purchase property in Japan regardless of visa status, major Japanese banks strictly enforce two critical criteria for loan approval.
1. Permanent Residence Status
Japanese mortgages offer exceptionally low interest rates — rates have crept up recently, but remain low compared to an average of around 6% in many countries overseas. Because of this, domestic banks have near-zero risk tolerance, and many require applicants to hold Permanent Residency (PR) to guarantee long-term residence in Japan.
Without PR: buyers typically need a larger down payment (20–30%), a Japanese citizen or PR-holding spouse to act as guarantor, or access to specialized non-PR lender programs. These programs generally carry higher interest rates, so it’s worth checking whether the lender allows you to switch to a standard rate once you obtain PR.
2. Japanese Language Proficiency & Direct Bank Verification
Under Japanese legal compliance requirements, loan applicants must fully understand the financial and legal terms of their mortgage.
- The Phone Screening Rule: during underwriting, most banks conduct a mandatory verification call directly with the buyer.
- No Interpreters Allowed: banks strictly prohibit real estate agents, spouses, or translators from taking this call or completing application forms on your behalf. If you can’t converse in and read basic financial Japanese during these interactions, a traditional bank application will likely be declined.
How We Help You Navigate This
If you don’t hold Permanent Residency or aren’t fluent in Japanese, you still have options. We work directly with specialized bilingual financial institutions and non-bank lenders offering tailored financing for foreign executives and residents.
Contact our team today to review your eligibility before you start your property search.
 記事を執筆したエージェント
- このエージェントに相談する
-
 080-4171-9123